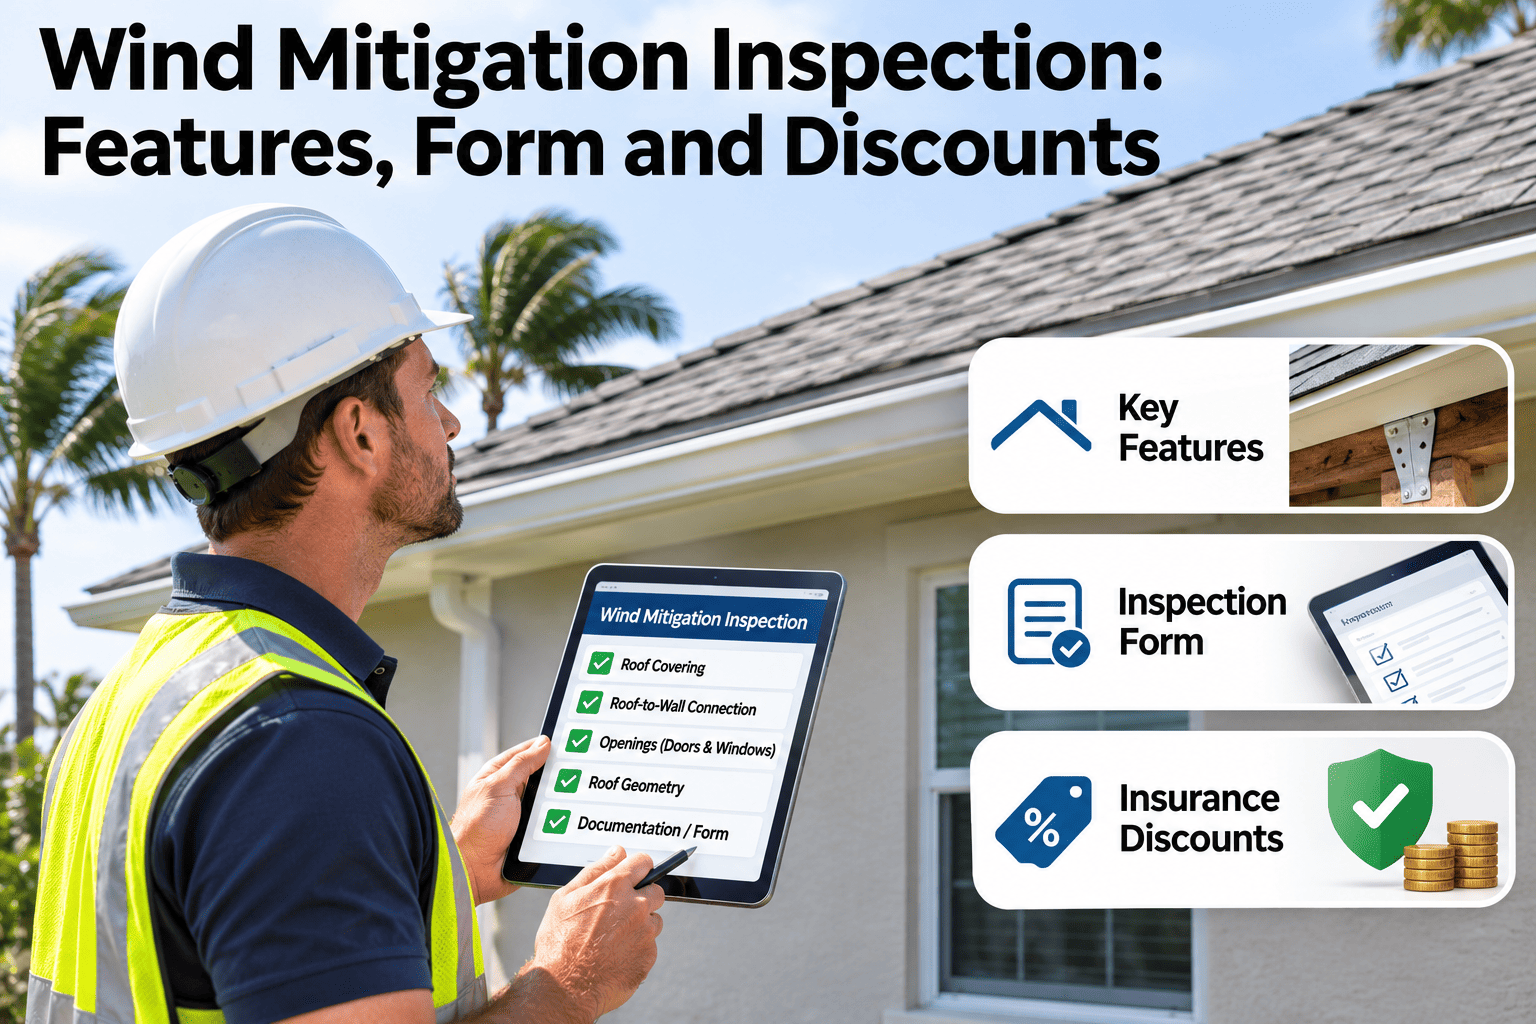
A wind mitigation inspection is the rare report that can lower a homeowner's bill rather than add to it. In Florida it is documented on one standardized form, the OIR-B1-1802, and state law requires carriers to credit the wind-resistant features it verifies. For an inspector, the job is to read seven construction features correctly and photograph each one. This guide walks through all seven, the connection that unlocks the biggest credit, and the form that carries it to the insurer. Run your wind mitigation reports in HomeInspecto.
Specialty inspection guide
Wind mitigation: the features, the 1802 form, and the discount
The inspection reads a home from the roof covering down to the openings. Each layer it verifies can lower the windstorm premium — if it is documented and photographed the way the form requires.
- Roof coveringMaterial & code compliance
- Roof deckFastener type & spacing
- Roof-to-wallToe nails to double wraps
- OpeningsImpact & debris protection
What a wind mitigation inspection is
It is a standardized look at how well a home resists hurricane-force wind, documented on Florida's Uniform Mitigation Verification Inspection Form — the OIR-B1-1802. Carriers use it to apply premium credits, and Florida Statute 627.0629 requires them to offer those credits for verified features. The savings apply to the windstorm portion of the premium.
This is primarily a Florida program, though other hurricane-prone states run similar schemes under their own forms. The credits, their size, and the rules vary by carrier and by state, so treat specific discount figures as carrier-dependent. One practical note: inspectors need attic access to verify the roof-to-wall connection — no access, no credit for that line — see how HomeInspecto captures it in a demo.
The seven features inspected
The 1802 form rates a home across seven construction features. Each one is scored independently, and each contributes its own credit.
- 1Building code era. The year built and the code in force set the baseline for how the home was engineered against wind.
- 2Roof covering. The material and whether it meets the Florida Building Code — shingles, tile, or metal, and their compliance status.
- 3Roof deck attachment. How the deck is fastened — staples at the weak end, ring-shank nails at close spacing at the strong end.
- 4Roof-to-wall connection. How the roof is tied to the walls — toe nails, clips, single wraps, or double wraps. The single biggest credit.
- 5Roof shape. A hip roof, where every slope meets the wall, resists uplift better than a gable or other shape.
- 6Secondary water resistance. A sealed barrier under the covering that keeps water out if the covering is lost.
- 7Opening protection. Impact-rated windows, doors, and shutters that guard against wind-borne debris.
Each feature is a separate line on the form, and each needs its own photo. Capture all seven on one mobile form with HomeInspecto.
Roof-to-wall: the biggest single credit
No feature moves the premium more than how the roof is fastened to the walls. The stronger the connection, the larger the credit — and the gap between the weakest and strongest is wide.
A metal connector that wraps over the truss and is nailed on both sides earns far more than a few angled nails. It is the line worth getting into the attic to verify. See the connection decoder in a demo.
Roof deck and roof shape
-
Roof deck attachment
Runs from staples at the weak end to 8d ring-shank nails at close spacing at the strong end. The fastener type and how far apart they sit decide the credit.
-
Roof shape
A hip roof, where all slopes angle back to the walls, sheds wind better than a gable or flat shape and earns a stronger geometry credit.
Both are read from the attic and the exterior, and both need a photo on the form. Prompt every required shot with HomeInspecto.
Opening protection
Windows, doors, skylights, and garage doors are the home's weak points in a storm. To earn the opening-protection credit, every opening generally has to be protected — one unprotected window can cost the whole credit.
- Impact-rated windows and doors that pass large- and small-missile tests
- Storm shutters rated for wind-borne debris across all openings
- Rated garage doors, a common weak link when overlooked
The credit is all-or-nothing on coverage, so the inspection has to account for every opening. See opening logging in a demo.
Seven features, one labeled report
Photograph each feature, tag its classification, and hand the carrier a complete 1802 they accept the first time.
The form, the photos, and the clock
- 1 photoAt least one proof photo per rated feature, under the revised form
- 5 yearsHow long a completed 1802 stays valid
- AtticAccess needed to verify roof-to-wall, or that line scores nothing
The 1802 was revised effective April 1, 2026, adding design-wind-speed region and roof-slope fields and requiring proof photos for each feature. A feature you cannot photograph is a feature the carrier cannot credit — which makes the field record the whole job. Keep the photo proof organized in HomeInspecto.
How HomeInspecto gets the 1802 right
-
Feature-by-feature template
All seven categories in form order, so no rated line is left blank.
-
Proof-photo prompts
The form flags the required shot for each feature before you leave the attic or the yard.
-
Connection pick-lists
Tap toe nail, clip, single wrap, or double wrap, so the roof-to-wall line is classified consistently.
-
Opening inventory
Log every window, door, and garage door, so the all-or-nothing credit is never assumed by mistake.
-
Carrier-ready export
Turn the field record into a clean document the homeowner can forward to the insurer the same day.
-
Record per property
Every 1802 and photo stays on file, ready for the renewal before the five years run out.
A complete form, proof on every line, and a faster path to the credit. Book a demo on your own wind-mit flow.
Frequently asked questions
What is a wind mitigation inspection?
A standardized look at a home's hurricane-resistant features — roof covering, deck, roof-to-wall connection, shape, water resistance, and openings — recorded on Florida's OIR-B1-1802 form so the carrier can apply premium credits. See the flow in a quick demo.
What is the OIR-B1-1802 form?
The Uniform Mitigation Verification Inspection Form — Florida's single statewide document for wind mitigation. Every Florida carrier accepts it, it rates seven features, and it must be signed by a qualified inspector.
Which feature gives the biggest discount?
Usually the roof-to-wall connection. Double wraps or clips earn far more than toe nails, which is why inspectors get into the attic to verify it. A clear proof photo is what secures the credit — start a free trial.
How long is a wind mitigation report valid?
A completed 1802 is generally valid for five years. Renewing before it expires keeps the credits flowing without a gap in coverage.
How much can wind mitigation save?
The credits are cumulative and apply to the windstorm portion of the premium, but the exact amount depends on the home's features, the carrier, and the state. Treat any single figure as carrier-dependent. See how the features map to the form in a demo.
Read the roof, earn the credit
Deliver a complete OIR-B1-1802 with proof on every line
Feature templates, proof-photo prompts, and connection pick-lists — so the homeowner's credit is never lost to a missing shot.


