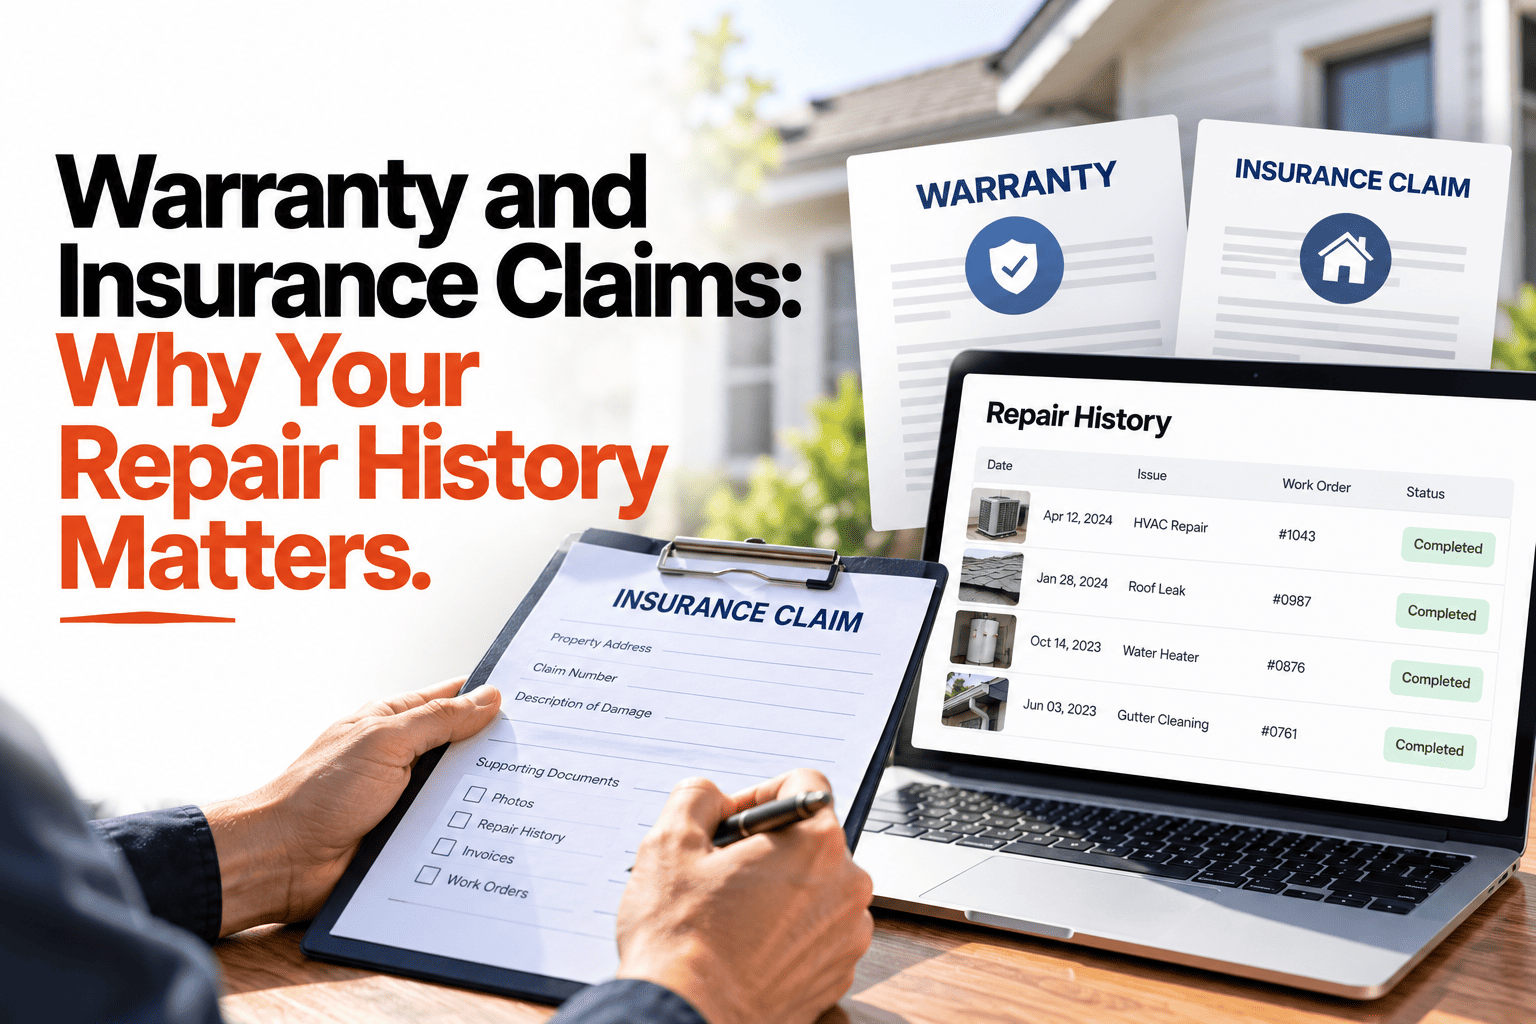
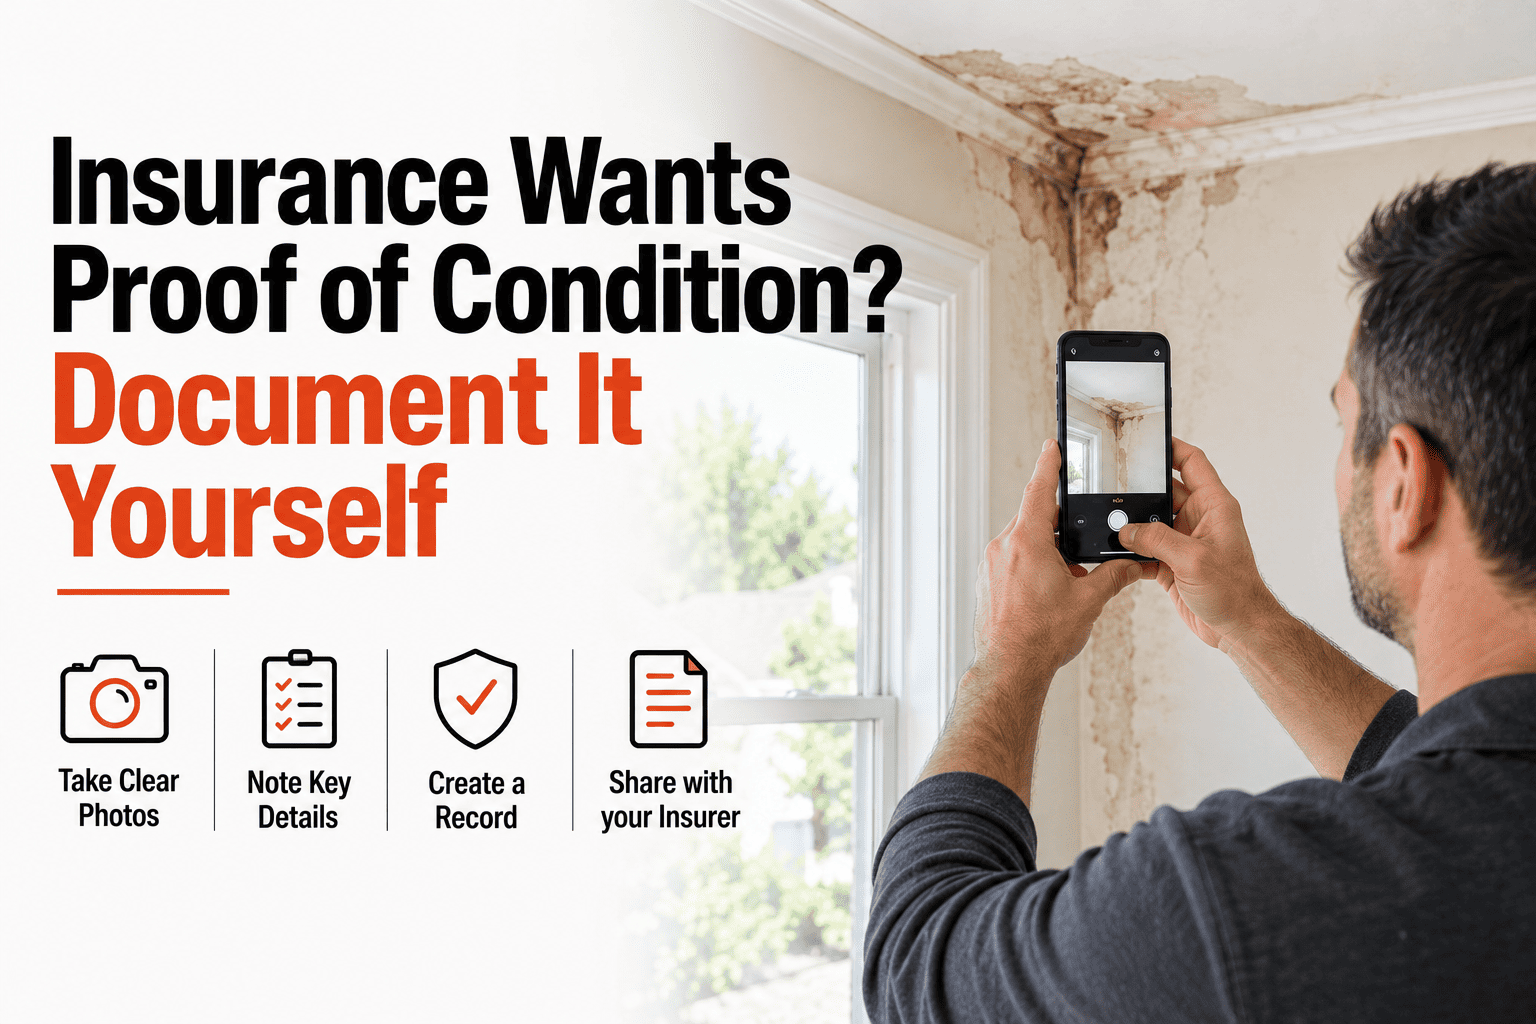
Insurance carriers are asking for more than they used to. A renewal that once required nothing beyond a premium payment now sometimes comes with a request for current photos of the roof, the water heater, or the property's overall condition. A claim that once moved on your word now moves faster with a dated record showing what the property looked like before the damage happened. Waiting until a carrier asks — or worse, waiting until you need to file a claim — puts you in a weaker position than having the documentation ready in advance. This guide covers what carriers typically want to see, how to build that record yourself, and why doing it before renewal or a claim changes the outcome. If you want a guided tool for building this record, book a demo.
Condition Record — For Insurance Purposes
Carriers Are Asking for Proof. Have It Ready.
A dated, photo-backed condition record built before renewal or a claim — not scrambled together after your carrier asks.
What Carriers Typically Want to See
Requirements vary by carrier and policy, but a few categories come up consistently across renewal requests and claims documentation.
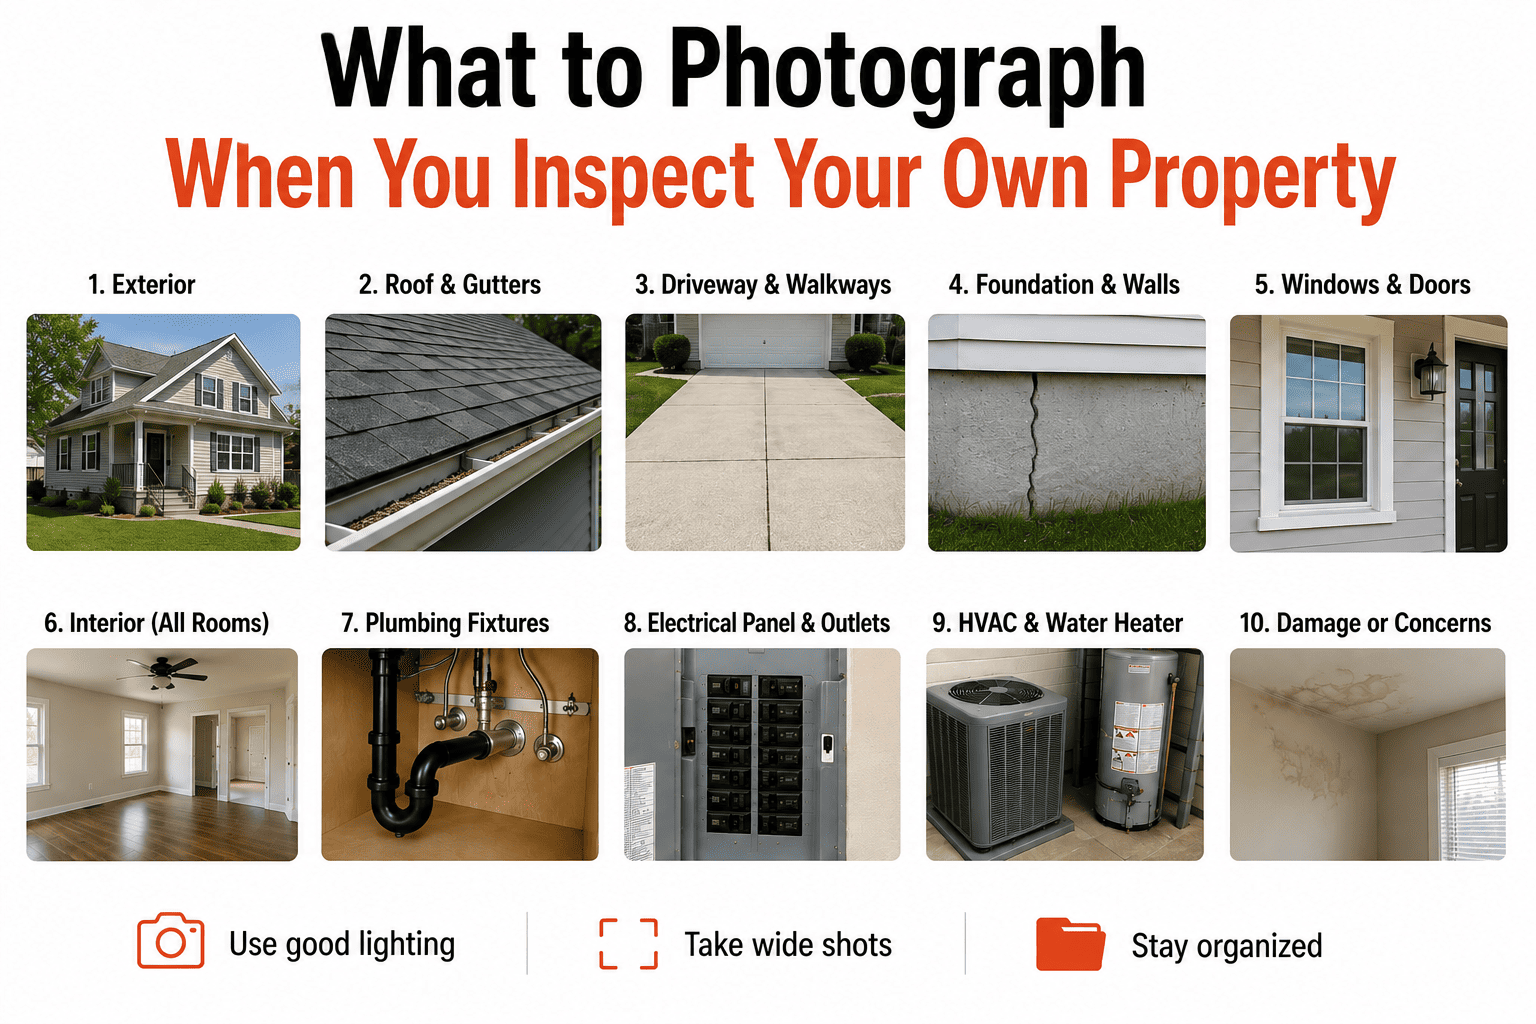
Roof condition
Age, visible wear, and any damage — often the single most-requested item on renewal, especially in storm-prone regions.
Water heater and major systems
Age and condition of the water heater, HVAC, and electrical panel — systems most likely to cause a claim if they fail.
Overall exterior condition
Siding, foundation, and general upkeep — carriers use this to assess ongoing risk, not just damage history.
Pre-loss condition of contents
A room-by-room record of belongings and their condition, useful if you ever need to file a contents claim.
Dated, timestamped photos
Photos with a clear date attached — proof of when the condition was documented, not just what it looked like.
Before Renewal vs. After a Claim
The difference between having this record ready and not having it shows up at two specific moments — and both go more smoothly with documentation already in hand.
At renewal
If your carrier requests current condition photos, you can respond same-day with an organized, dated report instead of scrambling to take photos under a deadline — and a well-documented property can support smoother renewal terms.
After a loss
A pre-loss condition record establishes what the property looked like before the damage, which supports your claim without relying on memory or reconstructing details after the fact.
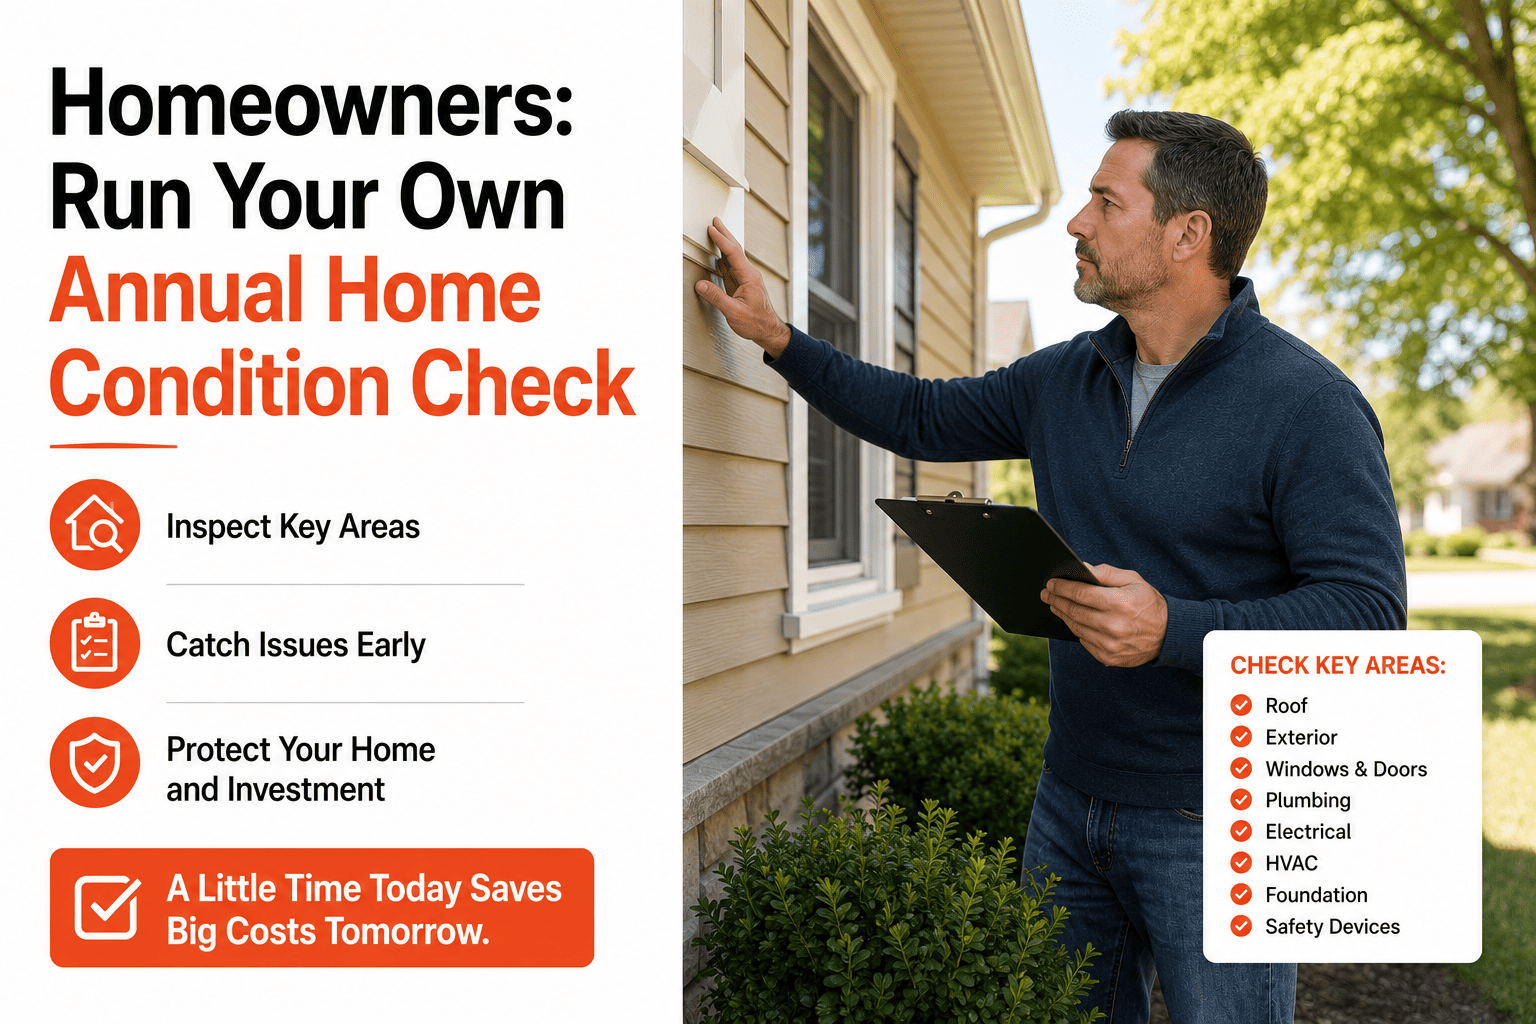
Build the record before you need it. A walkthrough today gives you a dated, photo-backed condition report ready for whenever your carrier asks.
Frequently Asked Questions
Will my insurance company accept a self-documented condition report?
Many carriers accept homeowner-submitted photos and documentation for routine renewal requests. For a specific claim or complex situation, check with your carrier or agent about what format they require, but a dated, organized report is a strong starting point either way.
How often should I update this documentation?
Once a year is a reasonable baseline, ideally timed before your policy renewal. Update it immediately after any major repair, renovation, or new purchase that changes the property's condition or contents.
What's the difference between this and a home inventory?
A home inventory typically focuses on belongings and their value for contents coverage. A condition report covers the structure and systems — both are useful, and often overlap in a single walkthrough.
Can I generate this report quickly before a renewal deadline?
Yes. A guided walkthrough on your phone can produce a complete, dated report in well under an hour, which is often fast enough to meet a carrier's request window. Book a demo or start a free trial.
Don't Wait for the Carrier to Ask
Build a dated, photo-backed condition record now — before renewal, before a claim, before you need it.